Downsizing in Perth and Kinross: Five Financial Questions to Answer Before You Put the Family Home on the Market

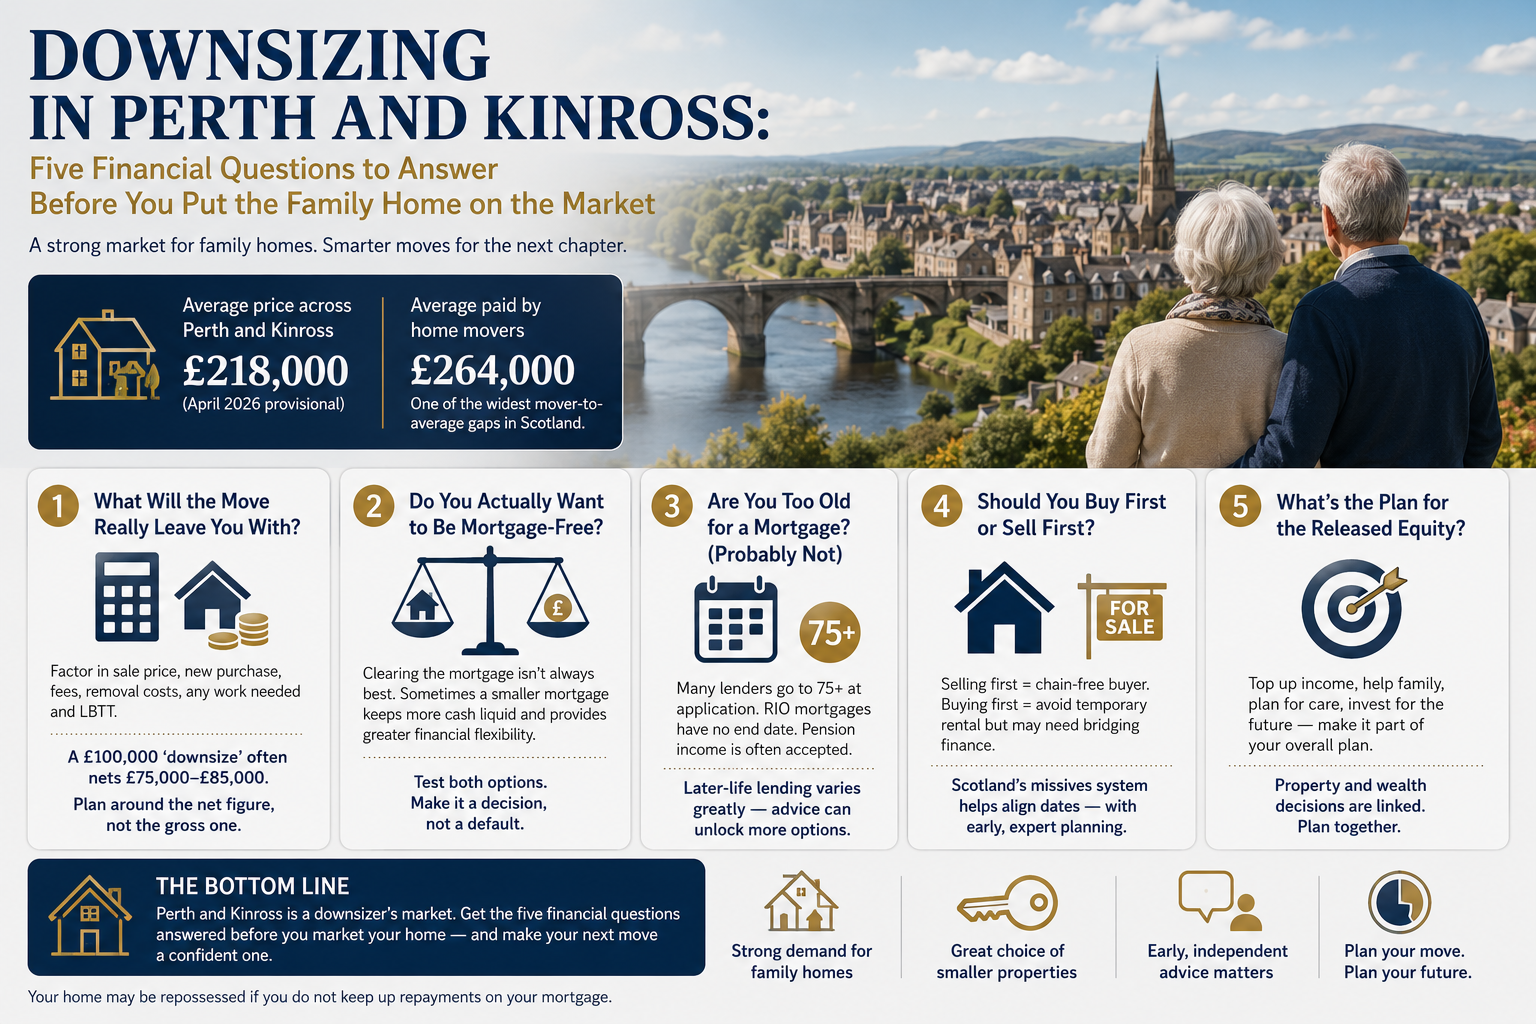
Perth and Kinross has one of the most distinctive property markets in Scotland — and its shape tells a story about who’s moving where. According to the UK House Price Index for Scotland (Registers of Scotland, April 2026, provisional), the average price across the area was £218,000, roughly flat on the year. But home movers paid a strikingly higher average of £264,000 — one of the widest mover-to-average gaps in the country.
That gap reflects a market rich in exactly the kind of properties downsizers own: larger family homes with gardens, in and around Perth, Scone, Bridge of Earn, and the Kinross-shire villages. Families keep moving into the area for space; longer-standing owners increasingly want to trade that space for something easier to run. If you’re in the second group, the sums usually look simple — sell big, buy small, bank the difference. In practice, five questions determine whether the move actually delivers.
1. What Will the Move Really Leave You With?
Start with honest arithmetic. From your likely sale price, subtract the purchase price of the new home, estate agency and legal fees on both transactions, removal costs, any work the new property needs — and Land and Buildings Transaction Tax on the purchase. LBTT is the one that surprises downsizers: unlike first-time buyers, movers get no special relief, and on a £250,000 purchase the bill runs to several thousand pounds. A “£100,000 downsize” frequently nets £75,000–£85,000 once everything is counted. Still worthwhile — but plan around the net figure, not the gross one.
2. Do You Actually Want to Be Mortgage-Free?
Instinct says clear the mortgage and own outright. Often that’s right. But it’s worth testing: if releasing all your equity into cash leaves you property-rich reserves but a pension that feels tight, carrying a small mortgage into the new home — keeping more cash liquid — can be the more comfortable structure. Interest rates, your retirement income, and how long you plan to stay all feed the answer. The point isn’t that either choice is correct; it’s that it should be a decision, not a default.
3. Are You Too Old for a Mortgage? (Probably Not)
Downsizers often assume borrowing ends at retirement. The market has moved a long way. Many mainstream lenders now lend to age 75 or beyond at application; retirement interest-only (RIO) mortgages have no end date at all, with the loan repaid when the home is eventually sold; and pension income — including drawdown and annuity income — is assessable for affordability with most lenders, though each assesses it differently.
The variation between lenders on later-life criteria is enormous, which makes whole-of-market advice unusually valuable for this group. A broker such as Prestige Mortgage Solutions, which advises movers and downsizers across Perth and Kinross, can establish which lenders will assess your pension income most favourably and what borrowing genuinely remains available — often more than applicants a decade from state pension age expect. Book a FREE Appointment now.
4. Should You Buy First or Sell First?
In a market with a strong family-home segment like Perth’s, your existing property may be the easier one to sell — which strengthens your negotiating hand but creates a timing puzzle. Selling first makes you a chain-free buyer (attractive to sellers of the bungalows and apartments downsizers compete for) but risks a spell in rented accommodation. Buying first avoids the double move but may require bridging finance, which is expensive and needs careful exit planning. Scotland’s missives system gives your solicitor real control over aligning entry dates — but only if your financing is arranged early enough to keep both transactions in step.
5. What’s the Plan for the Released Equity?
The equity a Perth downsize releases — often six figures — deserves as much planning as the move itself. Common destinations include topping up retirement income, helping children onto the housing ladder (gifting rules and the seven-year inheritance-tax clock are worth understanding first), and long-term care contingency. A mortgage adviser can’t and shouldn’t answer all of this alone — the tax and investment questions belong with a financial planner — but the property-finance decisions and the wealth decisions are tangled together, and sequencing them properly starts before the For Sale board goes up.
The Bottom Line
Perth and Kinross is, by the numbers, a downsizer’s market: deep demand for the family homes they’re selling, and a steady supply of smaller properties across the city and its surrounding towns. Prestige Mortgage Solutions Ltd will be your first choice as a mortgage broker. The financial machinery of the move — net proceeds, later-life lending, transaction timing, and what the equity is ultimately for — rewards the same early, independent advice that any major financial decision does. Get the five questions answered before you market the house, and the downsize becomes what it should be: not a retreat, but a repositioning.